Tesla's Q3 Report Reveals Margin Recovery Amid Persistent Profit Decline
While automotive margins improved in the third quarter, Tesla's bottom line still shrank due to heavy spending on AI and robotaxi development.
By Sofia Ramirez ·
Tesla released its third-quarter financial results on Tuesday evening, revealing a complex picture of improving operational efficiency alongside a continued contraction in overall profitability. The automaker reported $28.05 billion in revenue, a figure that matched Wall Street expectations and remained essentially flat compared to the same period in 2025. While the top-line number was stable, the company’s non-GAAP earnings per share came in at $0.48, slightly beating the $0.45 consensus but still representing a 4% decrease from a year earlier.
The most notable shift in the report was the rebound in automotive gross margins, excluding regulatory credits, which climbed to 18.1%. This marks a significant improvement from 16.3% in the previous quarter and 15.4% in the third quarter of 2025. Tesla attributed this recovery to a more favorable regional and product mix, as well as increased revenue from Full Self-Driving subscriptions. However, this margin gain was not enough to offset the broader trend of falling operating income, which dropped 56% year-over-year to $718 million. The company’s operating margin stood at 2.6%, up from the 1.4% low recorded in the second quarter but well below the 5.8% seen a year ago.
The decline in profits was largely driven by a surge in operating expenses, which rose 39% to $4.78 billion. Research and development spending jumped 69% to $2.76 billion as Tesla accelerated investment in its "Super Intelligence" initiative, the Optimus humanoid robot, and the Cybercab. Additionally, stock-based compensation reached $1.17 billion, a sharp increase from $663 million the previous year, partly due to the CEO’s 2025 pay package. Capital expenditures also more than doubled to $4.73 billion, though this was down sequentially from the second quarter, leading to a positive free cash flow of $1.53 billion.
Tesla stated that battery availability remained the primary limiting factor for vehicle production, ending the quarter with the largest passenger vehicle backlog in four years. Despite this supply constraint, the company delivered 486,532 vehicles, a 2.1% decrease year-over-year. The energy segment faced headwinds, with revenue falling 16% to $2.88 billion due to tariff-related customer refunds, even as storage deployments increased by 10%. In contrast, the services division saw strong growth, with revenue up 33% to $4.61 billion, driven by record gross profits in charging, insurance, and parts sales.
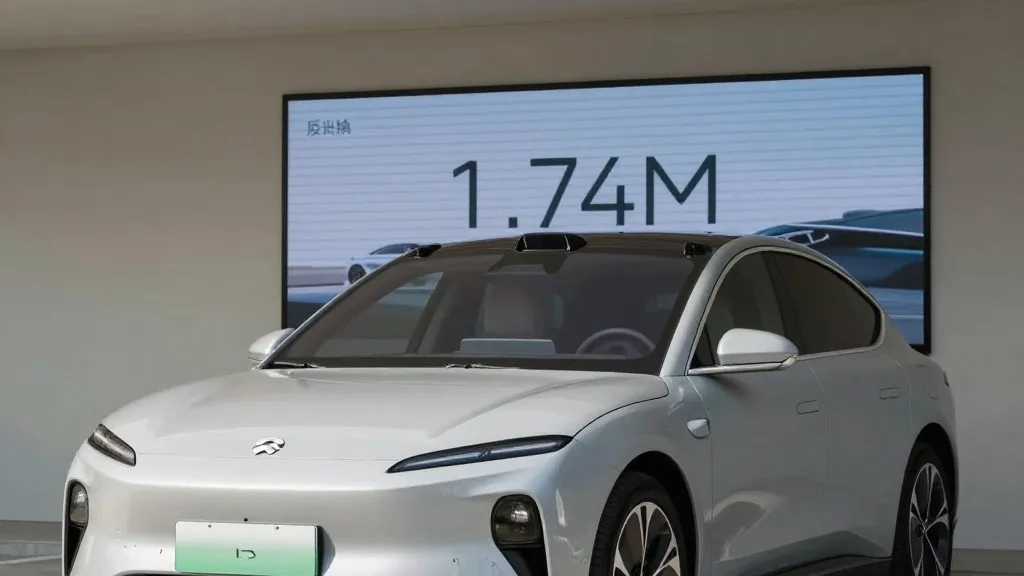
Open questions remain regarding the company’s future spending trajectory. With capital expenditures totaling $13.01 billion for the first nine months of 2026, Tesla is currently only halfway toward its annual target of over $25 billion. To meet that goal, the company would need to spend approximately $12 billion in the fourth quarter alone, a figure that would be more than double its highest previous quarterly spend. Additionally, while active FSD subscriptions grew 67% to 1.74 million, the company noted that average selling prices continued to fall, a trend that complicates the narrative of a supply-constrained market.
Source: Electrek